If you’re moving to Florida or buying an investment property here, odds are good your next home comes with a homeowners association. About 45% of Florida homes, roughly 3.9 million properties, are governed by an HOA, according to figures cited by ManageCasa in 2026. In the newer master-planned communities around Orlando, Tampa and Southwest Florida, it’s closer to the rule than the exception.
That isn’t a bad thing on its own. A well-run HOA keeps the pool clean, the entrance landscaped and the neighbor’s boat out of the driveway. A poorly run one can hit you with a five-figure special assessment, ban the short-term rental you were counting on, or fine you for a trash can left out a day too long. You won’t find the difference in the listing photos. You’ll find it in the paperwork, which is why the time to read it is before closing, not after.
HOA vs. condo association: the Florida difference
In Florida, a homeowners association is governed by Chapter 720 of the Florida Statutes. You own your house and your lot. The association owns the common areas, such as the gated entry, clubhouse, pool and green space, and bills owners to maintain them.
A condominium association falls under Chapter 718, and the math is different. You own the interior of your unit, while the association is responsible for the building itself: the roof, the structure, hallways, elevators and, in most cases, the master insurance policy. That’s why condo dues in Florida run so much higher than HOA fees in single-family neighborhoods.
The distinction matters more than ever, because the post-Surfside reforms landed almost entirely on condos. If you’re coming from a state where condo fees are predictable, Florida’s newer rules on reserves and structural inspections deserve your full attention.
What your HOA fee actually pays for
What you pay depends on what the community offers. A subdivision with a retention pond and a few streetlights might charge very little. A gated resort-style community with a lazy river, fitness center and 24-hour security will charge a lot more.
| Item | Single-family HOA | Condo association |
|---|---|---|
| Common areas (gate, landscaping, pool) | Yes | Yes |
| Building insurance | No, the owner pays | Yes, master policy |
| Roof and exterior | Only in some townhome communities | Yes |
| Reserves for major repairs | Recommended | Required for buildings 3 stories and up |
| Water, trash or cable | Sometimes | Often |
| Typical monthly range | $150 to $800 or more | A few hundred to $2,000 or more |
To put real numbers on it: in Tampa Bay, a $1.5 million home in a gated South Tampa community might carry a $200 to $400 monthly HOA fee, while a $1.5 million condo downtown can run $1,200 to $2,500 a month. The gap is mostly insurance and building upkeep.
A low fee isn’t automatically good news. Sometimes it means the association hasn’t been saving for the day the clubhouse roof or private roads need replacing, and that bill eventually shows up as a special assessment.
The Florida laws that changed the rules
Florida overhauled its HOA law with House Bill 1203, signed in May 2024. By January 2026, all of its major provisions were in force. For buyers, three changes stand out. Financial transparency is now a legal obligation: associations must make budgets, financial statements and official records available to owners, and larger communities must post key documents online. Board members now have to complete mandatory education. And the law put new limits on fines and enforcement for minor violations.
On the condo side, House Bill 913 took effect July 1, 2025. It requires fully funded reserves, based on a Structural Integrity Reserve Study (SIRS), for buildings three stories or taller, while giving associations a few more financing tools to get there. In practice, many older buildings have raised dues sharply or passed large special assessments to catch up.
If you’re looking at a condo built in the 1980s or 1990s, this is the single biggest risk to understand. If you’re buying a house in an HOA community, HB 1203 works in your favor by giving you more access to the information you need.
Special assessments: the cost that isn’t in the price
A special assessment is a one-time charge the board approves when it needs money it doesn’t have in reserves. It might cover a new perimeter wall, resurfaced roads, a lost lawsuit or, in a condo, structural repairs flagged by an inspection.
Here’s the catch: the assessment is billed to whoever owns the home when it’s approved. If you close a month before the vote, it’s yours. That’s why you should read the last year or two of board meeting minutes. Big projects, contractor bids and worries about low reserves usually show up there long before the vote.
A quick example. You buy a $320,000 condo in a 1990s building with 120 units. The SIRS shows $3.6 million in concrete and balcony work needed over five years, and the reserve account holds $400,000. That leaves a $3.2 million gap, or about $26,700 per unit, more than 8% of your purchase price. The number was sitting in the SIRS before you signed.
Rental rules: the first thing investors should check
If you’re buying to rent, the HOA’s lease rules can matter more than the price. Many communities require a minimum lease term of six or twelve months, which rules out vacation rentals entirely. Others require board approval of every tenant, charge application fees or cap how many homes can be rented at once.
Florida law offers some protection. When an HOA amends its documents to prohibit or restrict rentals, that amendment generally applies only to owners who voted for it and to people who buy after it passes. But if the restriction is already on the books when you buy, it applies to you from day one. If you’re planning on Airbnb, check county and city rules too; our guide to vacation rentals and Airbnb in Florida shows why zoning matters as much as the HOA’s rules.
Communities built for short-term rentals near Disney, in Davenport, Kissimmee and along the 192 corridor, typically allow them by design. Outside those areas, most HOAs don’t.
How to vet an HOA before you buy
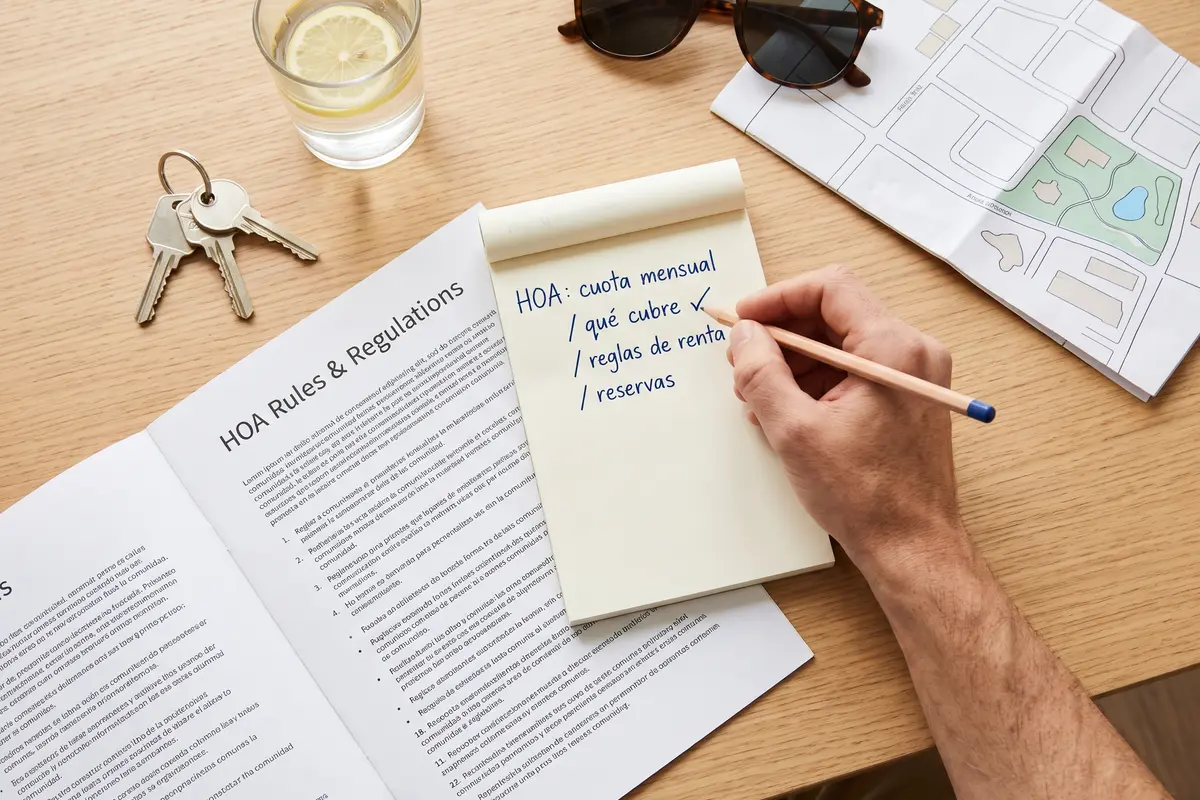
The safest approach is to request the association’s documents during your inspection period and actually read them. Here’s what to ask for:
- Governing documents. The declaration of covenants (CC&Rs), bylaws and rules. This is where you’ll find restrictions on rentals, pets, vehicles, renovations and common-area use.
- Current budget. It shows what it really costs to run the community and whether dues cover expenses.
- Reserve study or reserve schedule. Compare what’s saved with what major repairs will cost. For a condo three stories or taller, ask for the SIRS.
- Minutes from the last 12 to 24 board meetings. The best place to spot pending assessments, disputes with the management company or maintenance problems.
- Estoppel certificate. Issued by the association, it confirms what the seller owes, any approved assessments and current dues. Florida law caps what the association can charge for it.
- Delinquency rate. If more than 10% to 15% of owners aren’t paying, the association has less revenue and may raise dues on everyone else.
- Pending litigation. A lawsuit against the association can lead to an assessment or make it harder to get a mortgage.
- Insurance. For condos, confirm the master policy’s coverage and the hurricane deductible, which is often passed on to owners.
It’s a lot of reading, and it helps to have someone who knows what to look for. Our legal advice to protect your real estate investment in Florida includes a review of the HOA package during your inspection period, while you can still negotiate or walk away.
How much the HOA weighs on your returns
An HOA fee is a fixed monthly cost that comes straight out of your rent, so it hits your returns directly. Compare two similarly priced options in the Orlando area:
| Item | Townhome in Kissimmee | Condo in Orlando |
|---|---|---|
| Purchase price | $380,000 | $360,000 |
| Estimated monthly rent | $2,500 | $2,350 |
| Monthly HOA fee | $250 | $650 |
| Annual HOA cost | $3,000 | $7,800 |
| HOA as a share of annual rent | 10% | 28% |
With nearly identical rents, the condo leaves you $4,800 a year less, just on dues. On a $360,000 purchase, that knocks more than a full point off your cap rate. To see how the HOA stacks up against taxes, insurance and maintenance, check our breakdown of what it really costs to own property in Florida.
That doesn’t make the condo a bad buy. It may have a better location, less maintenance on your plate and building insurance baked in. It just means the fee, and the odds it goes up, belong in your numbers from day one.
Managing the HOA relationship from out of state
If you live in New York, Chicago or anywhere outside Florida, your property manager will handle most of the day-to-day relationship with the HOA: violation notices, tenant approvals, on-time dues and routine requests. A fine for an overgrown lawn seems trivial, but unpaid fines can pile up and, in some cases, turn into a lien.
Our property management services in Orlando include that coordination with the association, so community rules don’t turn into surprise costs.
It also helps to see where the HOA review fits in the overall purchase. Our step-by-step guide to buying a home in Florida shows when in the contract timeline to request and review the association’s documents.
Frequently asked questions about Florida HOAs
Are HOA fees mandatory in Florida?
Yes. If the property is in a community with a mandatory association, dues aren’t optional. If you stop paying, the association can charge interest, late fees and attorney’s fees, record a lien and ultimately foreclose.
How much are HOA fees in Florida?
It depends on the community. Single-family HOAs typically run from $150 to $800 or more a month, depending on amenities. Condo associations charge more because dues cover building insurance and upkeep, and luxury buildings can top $2,000 a month.
Can a Florida HOA stop me from renting my home?
Yes, if the restriction is already in the documents when you buy. If the association adopts it later, it generally applies only to owners who voted for it and to future buyers. Always read the lease rules before you sign, especially if you’re planning a vacation rental.
What is an estoppel certificate?
It’s a statement from the association confirming the seller’s account status: dues, unpaid balances, approved special assessments and other charges. It’s ordered before closing so the buyer doesn’t inherit the seller’s debts. Florida law caps the fee for issuing it.
How can I tell if an HOA is financially healthy?
Compare reserves with upcoming repairs, check the delinquency rate and read recent board minutes. A healthy association has adequate reserves, few delinquent owners and minutes without recurring fights over assessments or lawsuits.
A well-vetted HOA can protect your property’s value for years, and a poorly vetted one can eat into your returns. Let us review the HOA before you buy so you sign knowing exactly which rules and costs come with the home.